Early access for couples
Ours to spend this month.
Rich Life puts your conscious spending plan into practice. It counts every dollar once, files the routine, and warns you before an account dips. You make the calls.
Watch about 45 seconds. Maya and Theo are an invented household.
- $299.73in points left on the table, 71.7% capture across 284 purchases
- $929.34in monthly card credits unused this year
- $237/moset aside so yearly bills stop surprising you
- $1,223/yrin subscriptions that fund none of your priorities
- 16 / 16payments between the two of you, counted once
- Demo household: Maya and Theo, April to October 2026, computed by the app from invented transactions.
The app does the routine. You make the calls.
Everything below is the demo household, on screens from the real app.
One number for the month.
Home opens on what is guilt-free left this month for the two of you. Fixed costs, investing and savings come out first.
- What needs a decision sits right underneath.
- Tap any figure to see the rows behind it.
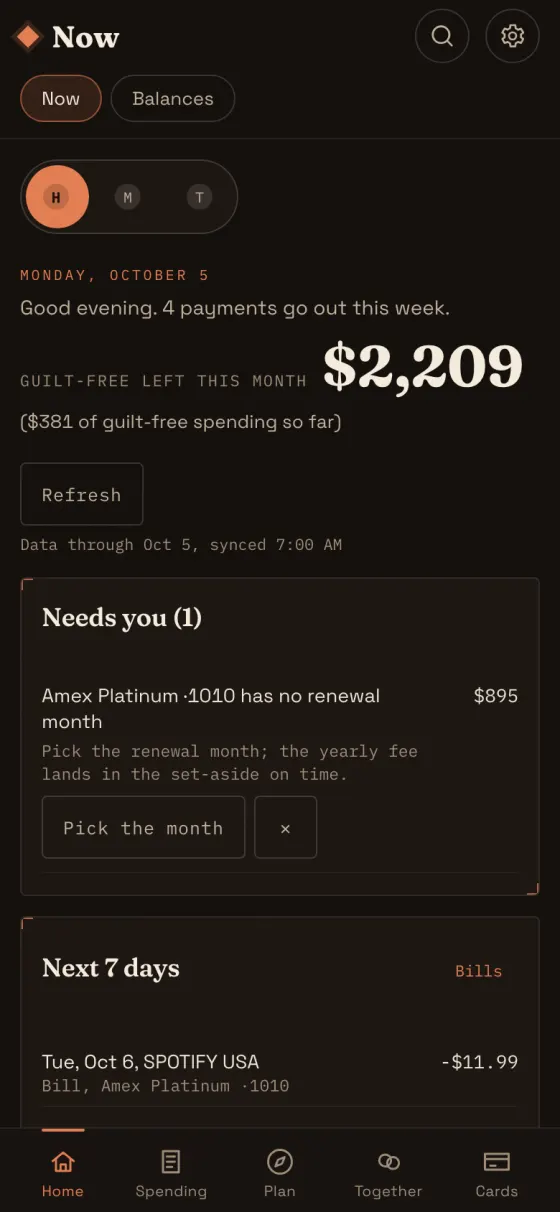
Fix it once.
Tell it that Instacart is Groceries. It re-files every matching charge, past and future, and you can undo it.
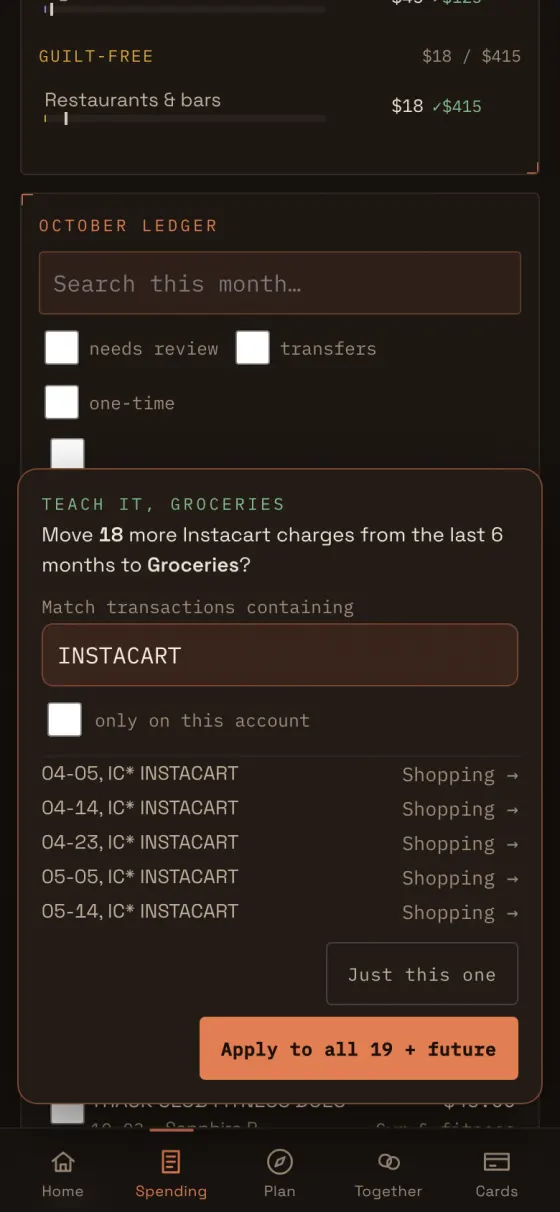
$299.73
in points left on the table, 71.7% capture across 284 card purchases
Did each charge go on the right card?
Every purchase is scored on what its points are worth, using only the cards you held that day. A miss is a real miss.
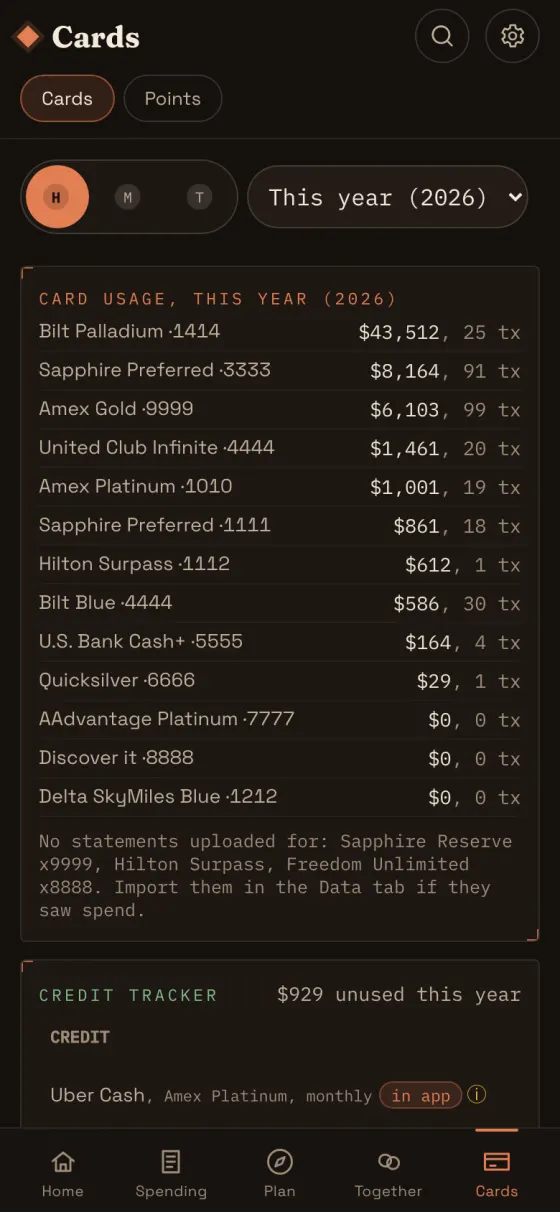
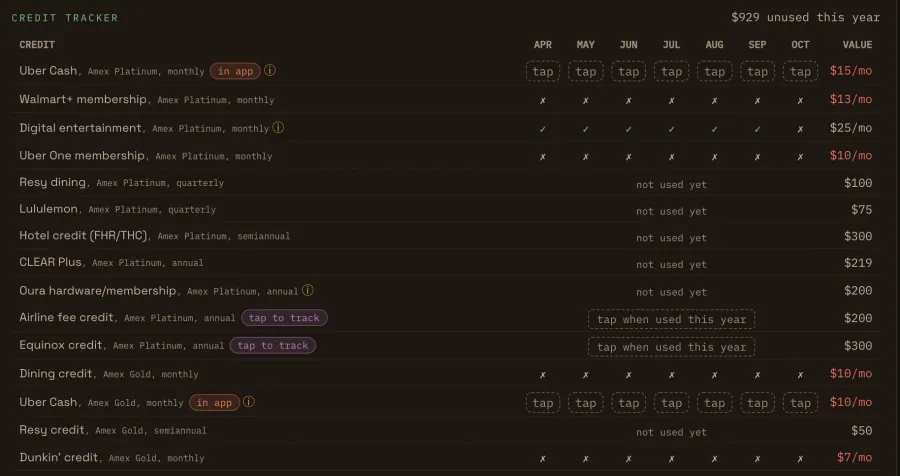
$929.34
in monthly card credits unused this year
Are you using the credits your annual fees pay for?
Credits are tracked month by month from what actually posted. Only finished months count as missed.
$237/mo
set aside so non-monthly costs stop being surprises
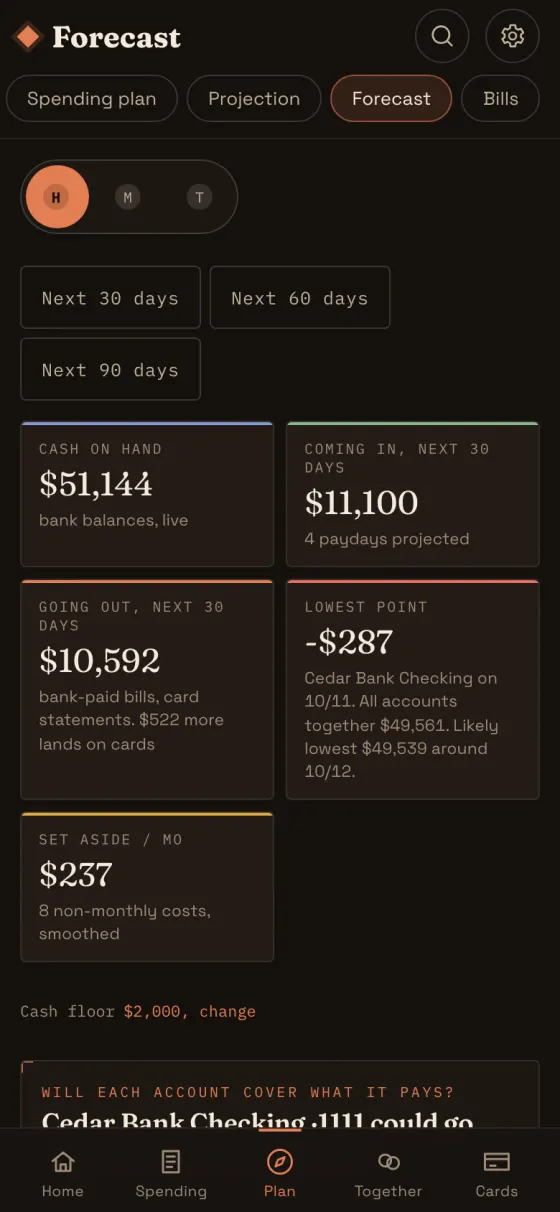
See the dip coming.
Each account is walked forward day by day. When a card statement would pull checking under your cash floor, it names the account and the move.
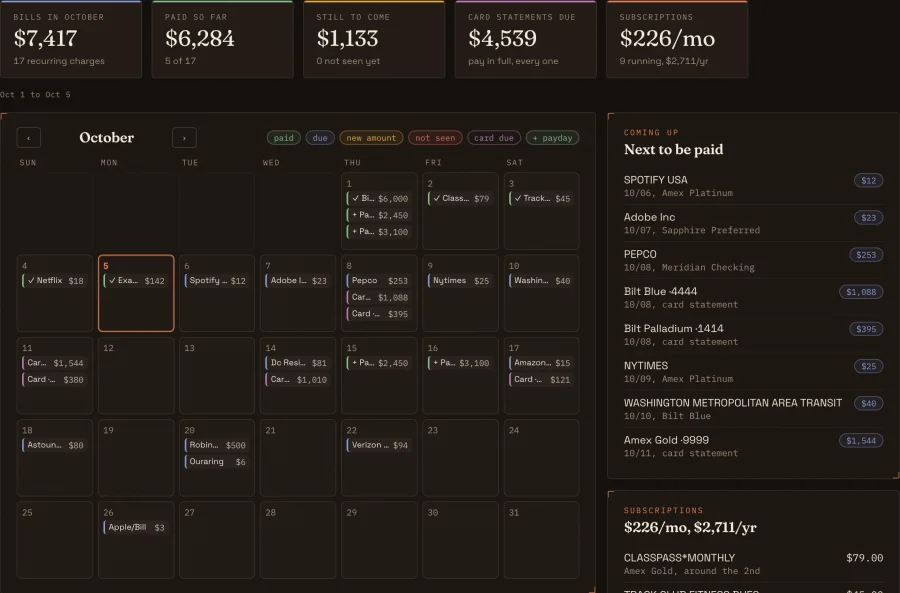
$2,711/yr
in 9 subscriptions, 7 of them ($1,223/yr) fund none of your priorities
What recurs, and what is it for?
Bills are found in the ledger, not typed in. A new amount is flagged, and a bill that has not shown up yet says so before you assume it was cancelled.
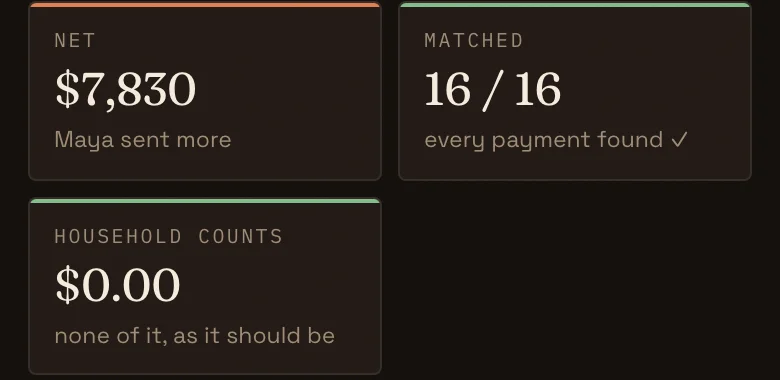
16 / 16
payments between the couple counted once
Two people, one household.
A payment between the two of you is not spending. Each of you sees it as "Between you", and the household counts none of it.
Numbers you can trust.
A money app that is wrong once gets double-checked forever. The figures come from code, not from a guess.
Counted once
A card payment shows up twice in raw statements: out of checking, and onto the card. Rich Life counts the spending once.
Your plan, as it ran
Fixed costs, investing, savings and guilt-free spending are measured against the last two finished months.
Your data in
Connect accounts through Plaid, or import statement files. Nothing is typed in by hand.
Tested rules
The money rules are pinned by automated tests, so each screen agrees with every other to the cent.
Nothing hidden
Every figure opens to the rows behind it, with the reason any row is not counted.
Yours, on your machine
Rich Life runs on your own computer and keeps your data there. Read the privacy note.
Opening to a small group of households.
Rich Life runs every day on real household money. We add households in small groups so each one is set up properly. No date is promised.
- Tell us about your household.How many accounts and cards you run, and whether you manage money with a partner.
- Nothing financial.The form asks for names, an email and which banks you use.
- We invite in small groups.You hear from us when your group is ready.